

Context and growth drivers
In a geopolitical scenario strongly conditioned by the conflict in Ukraine, which has placed the issues of energy security and diversification of supplies at the forefront, the new European REPowerEU plan represents the new North Star to strengthen the resilience of the energy system and accelerate the ecological transition.
Towards carbon neutrality in 2050
The international scenario – through the COP21 in Paris, the COP26 in Glasgow and the guidelines of the European Union – requires states and operators in the energy market to accelerate the path towards decarbonisation. The European Union, leading path to decarbonization, has set the target of carbon neutrality in 2050.
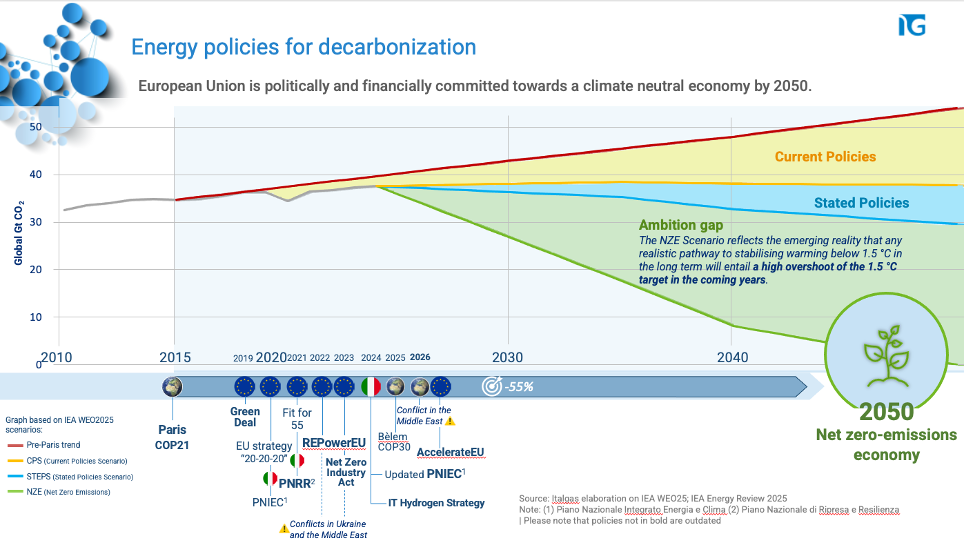
The energy transition, initially driven by the need to combat climate change, gained further momentum following the Ukraine conflict. The REPowerEU plan, unveiled by the European Commission in May 2022, seeks to emancipate Europe from Russian fossil fuels well ahead of 2030. This strategy is pivotal in expediting the shift towards sustainable energy and increase the resilience of European energy system. In 2021, Europe’s gas consumption was heavily reliant on Russian imports, constituting 38%. However, by 2025, the reliance significantly diminished, with Russian gas forming merely 12% of the imports (38 billion cubic meters vs +150 billion cubic meters in 2021), with the primary import channels being liquefied natural gas (LNG) and imports from Norway.
In this context, the gas DSO are called to play a key role in guaranteeing the energy security of the Union, equipping the respective countries with digital, smart and flexible networks, also able to boost the production of these gases and enable its widespread use.
European and national energy policies
| REPowerEU | Italy | |
|---|---|---|
| Green Gas | Accelerate green gases development, such as biomethane and hydrogen, compared to the previous Fit for 55 | The NECP’s revision suggests a goal to boost biomethane production to 5 Bcm by 2030. More than 2 Bcm of new production already funded through the incentive mechanism. |
| Infrastructure Development | Increase supply from non-Russian routes, new interconnections and maximization of LNG import capacity | Italy has diversified its LNG supply routes enhanced by regasification plants, and Russian gas imports have been reduced to ~1% in 2025. |
| Storage | EU gas storage to be filled up to at least 90% by end of summer | Italy successfully met its gas storage obligations in recent years |
| Energy Efficiency | Push for EU energy efficiency target for 2030 from 9% to 13% (vs 2020) | The NECP target for final energy consumption in 2030 is 94.4 Mtoe |
| FER Acceleration of renewable energy sources | Renewables acceleration, which will have to represent 45% of final energy consumption in 2030 (compared to the previous target of 40%) and will be driven by solar. | The NECP foresees a 40.5% share of renewable energy in total energy consumption by 2030. |
We invest to play a leading role in the energy transition
The strategic choices made in recent years by the Group have anticipated the approach of EU institutions and we are already aligned with the new targets and guidelines set in the REPowerEU.

We believe that our and other gas infrastructures will continue to play a key role in the energy transition ensuring energy system the needed flexibility, security and climate change resilience. The most important challenge for DSOs will be to guarantee their network is able to distribute and dispatch renewable gases such as biomethane, synthetic methane and green hydrogen. Having a “full digital” network is the technical precondition for effectively managing the distribution of renewable gases.
Italgas’ Strategic Plan is designed to support and foster the energy transition and contribute to security of supply. We are investing to repurpose and upgrade our network to increase its efficiency and resilience and enable green gases distribution. We are also committed to improve the energy efficiency and to achieve the decarbonization of our operations.
Our strategy, in continuity with previous years, is built taking into account several scenarios, both qualitative and quantitative, including those specifically related to climate change and considered the emerging related risk and opportunities (physical and transitional) for the company and its targets. Among the scenarios considered we use:
- Climate Physical Scenarios: RCP 1.9, RCP 2.6, RCP 4.5, RCP 8.5;
- Climate Transition and Energy Scenarios: IEA (CPS, STEPS, NZE, APS) described in the World Energy Outlook 2025 (the new analysis does not include APS scenarios), providing global CO2 emissions trend and energy consumption evolution in volumes and mix; ENTSOG Distributed Energy and Global Ambition Scenarios provide EU total energy demand and gas/hydrogen demand outlook. For green gases demand and prices evolution we use also IRENA “EU Energy Transition Outlook” and EBA for biomethane potentials. At national level, we use Snam-Terna scenario analysis for Italy and Desfa Forecast Study for Greece, as well as National Energy and Climate Plans – PNIEC/NECP – and the Italian Hydrogen Strategy. All the scenarios envisage an acceleration on energy transition, in line with RCP 1.9.
The scenarios analysis allows us to build solid assumptions for our strategic planning (e.g., gas demand, commodities prices, inflation, interest rates outlook etc.).
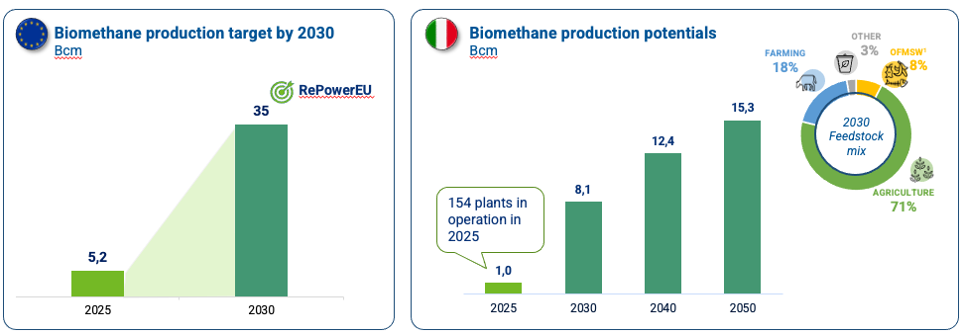
The REPowerEU plan sees a strong growth in biomethane production and hydrogen production and imports by 2030. For biomethane the new 2030 target of 35bcm doubles the previous one, while for hydrogen production and import is set to reach 20mt by 2030 (4 times the Fitfor55 target).
Italy currently has 154 active biomethane plants producing approximately 0.96bcm/y, with production expected to accelerate in the coming years.
Regarding hydrogen, we are developing several initiatives ongoing to ensure network readiness for hydrogen distribution and blending. We have already completed the analysis and preliminary technical assessment, where the preliminary results have showed high levels of compatibility with hydrogen blends up to 10% and we are identifying the investments necessary to upgrade the network.
The legislative and regulatory framework (Italy)
The distribution and measurement of natural gas is regulated by the Regulatory Authority for Energy, Networks and Environment (ARERA). Among its functions:
- The calculation and updating of the tariffs
- The provision of rules for access to infrastructure and for the delivery of the related services.
The rate system establishes in particular that the reference revenue for the formulation of rates is determined so as to cover the costs incurred by the operator and allow for a fair return on invested capital.
Three cost categories are recognised:
- The cost of net invested capital for RAB (Regulatory Asset Base) purposes through the application of a rate of return of the same;
- Economic-technical amortisation/depreciation, hedging investment costs;
- Operating costs, hedging operational costs.
Currently, we are in the fifth regulatory period, started on January 1, 2020 and was initially set to end on December 31, 2025; however, its duration has been extended to cover both 2026 and 2027 as well.